
 dinero_admin
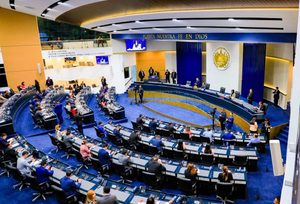
The Legislative Assembly approved, with 60 votes, five reforms that extend the period for public and private sector workers, pensioners, and alimony recipients to receive various year-end financial benefits. The modifications will allow advance payments starting october 1st and also stipulate that bonuses of up to US$1,500 will not be subject to income tax withholding.
Representative Caleb Navarro of the Nuevas Ideas party explained that the measures aim to ensure families have these funds available before december to cover expenses, meet obligations, and manage their finances. He also noted that the changes offer employers more options for scheduling these payments.
One of the reforms modifies Articles 197, 200, and 202 of the Labor Code. The main change establishes that workers’ Christmas bonuses can be paid starting october 1st, instead of october 20th as currently stipulated by law.
The reform also sets december 12th as the reference date for calculating the proportional Christmas bonus. It also maintains the right to proportional payment for those who have not completed the required service time to receive the full bonus or who are dismissed in the cases established by law.
In the case of pensioners, the Assembly amended Articles 97 and 153 of the Comprehensive Pension System Law to advance the payment of the Christmas pension and the annual additional benefit. These funds can be disbursed from the first business day of october until the fifth business day of december.
Another modification concerns child support payments. The deputies amended Legislative Decree No. 140, dated november 6, 1997, to allow the 30% withholding of the Christmas bonus for these obligations to be made from october 1st and delivered until december 20th.
For public employees, the amendment to the Law on Additional Cash Compensation extends the period for receiving this benefit. Payment can be made from october 1st to december 20th, giving institutions and workers a longer period to organize its delivery and disbursement.
Furthermore, the approved transitional provisions establish that the Christmas bonus and additional cash compensation contemplated in the Labor Code and the Law on Additional Cash Compensation will be considered non-taxable income up to US$1,500. Therefore, when the benefit is of this amount or less, no Income Tax withholding will apply.
In cases where the Christmas bonus exceeds US$1,500, the withholding will only apply to the excess. Navarro said that this measure aims to allow workers to access the benefit up to that limit without income tax deductions and noted that this provision has been approved annually by the Assembly.
You can also read: