
 dinero_admin
The Legislative Assembly has ratified two international agreements aimed at preventing companies and individuals from being taxed twice on the same income, once in El Salvador and once in the country with which they maintain economic relations. These agreements, signed with Türkiye and the United Arab Emirates, are intended to facilitate investment, strengthen trade, and combat tax evasion.
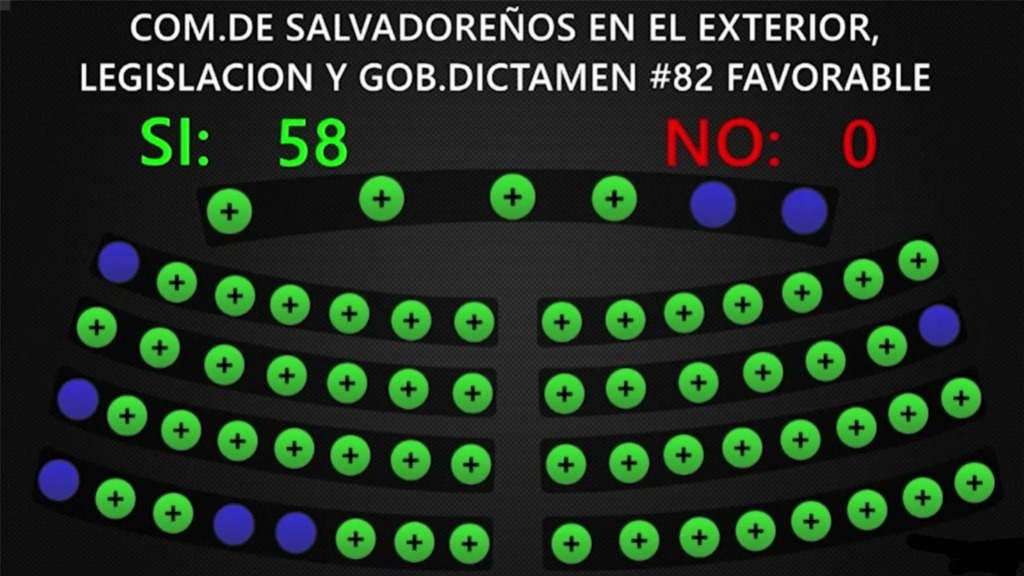
The first treaty, between El Salvador and Türkiye, received 58 votes in favor, while the agreement with the United Arab Emirates secured 59 votes. Both instruments were signed on September 25 in New York and establish rules for determining which of the two countries has the right to tax specific income.
Double taxation occurs when the same income is subject to tax in two different countries, for instance, when a salvadoran company conducts business abroad and is required to pay taxes on the same earnings in both the foreign territory and El Salvador. This situation can increase operating costs and diminish incentives for investing or expanding business operations beyond national borders.
The new agreements establish mechanisms to prevent such double taxation by allocating taxing rights between the signatory countries, based on the type of income and the specific terms set out in each agreement. Furthermore, they allow for the recognition or deduction of taxes paid abroad, ensuring that taxpayers do not face a redundant tax burden on the same income.
The agreement with Türkiye includes provisions covering various sources of income, such as business profits, dividends, interest, royalties, and gains from the sale of assets. It also incorporates procedures for resolving disputes regarding the application of tax rules and provides for the exchange of information between the tax authorities of both nations.
The agreement with the United Arab Emirates establishes rules for the taxation of income and capital, while also regulating the tax treatment of activities related to hydrocarbons, dividends, interest, royalties, capital gains, pensions, and employment income, among other items.
In addition to reducing the risk of double taxation, these instruments aim to close loopholes that could be exploited by individuals or companies to take advantage of differences between the tax laws of both countries and avoid meeting their tax obligations. To this end, they provide for greater cooperation between tax authorities and the exchange of information.
The ratification of these agreements represents a step toward strengthening El Salvador’s economic relations with Türkiye and the United Arab Emirates by offering greater clarity regarding the tax obligations of those who conduct business activities or generate income in both territories. The agreements will enter into force once the Salvadoran government completes the necessary legal procedures.
You may also want to read: