
 dinero_admin
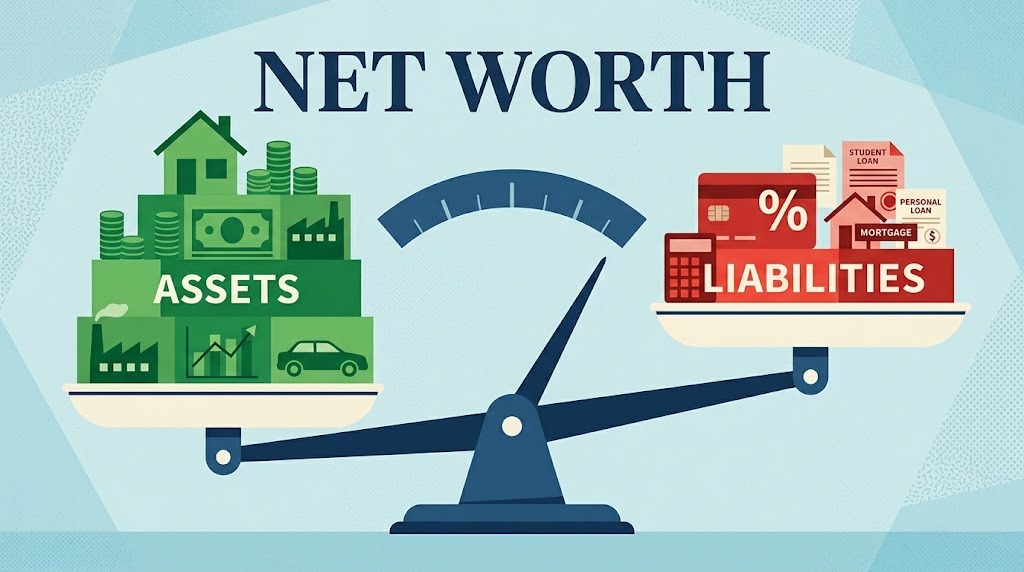
Knowing how much money you truly have involves more than just your monthly salary or the balance in your bank account. To get a more complete picture of your personal finances, it is important to calculate your net worth, a metric that represents the difference between the value of the assets and resources you own and the debts you still owe. According to Investor.gov, an educational portal from the U.S. Securities and Exchange Commission (SEC), this calculation provides a broad perspective on your overall financial situation.
To calculate it, the first step is to identify your assets, that is, all the goods and resources that hold economic value. This category includes money in bank accounts, savings, investments, real estate, and vehicles. Other valuable items can also be included, provided you can estimate their current market value. It is best to create a list and assign a realistic value to each item, rather than simply using the price originally paid when it was acquired.
The second step is to total your liabilities, which represent your outstanding financial obligations. These may include credit card balances, personal loans, auto loans, mortgages, and other debts. To ensure accuracy, you should record the remaining balance yet to be paid, not the original loan amount. Once all assets and liabilities have been identified, you can use a simple formula: net worth = total assets − total liabilities.
For example, a person with $4,000 in savings, a vehicle valued at $8,000, and a home with an estimated value of $70,000 has a total of $82,000 in assets. If you still owe US$45,000 on your mortgage, US$5,000 on your vehicle, and US$2,000 on credit cards, your total liabilities amount to US$52,000. Subtracting this from your assets, your net worth is US$30,000. This figure is for illustrative purposes and does not mean you have that amount of money immediately available, as a large portion of your net worth may be tied up in assets that would need to be sold to be converted into cash.
Calculating your net worth helps determine whether your financial situation is positive or negative. When your assets exceed your debts, the result is positive; when your obligations exceed your assets and resources, it is negative. However, a negative net worth does not necessarily mean that a person lacks income or cannot improve their financial situation. It can serve as a signal to review your financial commitments, establish payment priorities, and develop a plan to strengthen your economic position.
Another use for this indicator is that it allows for the setting of financial goals with greater clarity. For example, an individual can use it to assess their progress in reducing debt, accumulating savings, purchasing a home, or preparing for retirement. By performing the calculation periodically and keeping records, one can compare the results and determine whether their decisions help to increase their assets or reduce their liabilities. Investor.gov recommends reviewing one’s net worth at least once a year to track financial progress.
For the result to be useful, it is also important to keep values up to date and to avoid confusing net worth with the money available for immediate spending. A home may represent a significant portion of one’s assets, but it is not the same as cash that can be used to cover an emergency without selling the property or seeking financing. For this reason, it is advisable to review liquid savings, monthly income, and regular expenses separately. A budget helps identify how much money comes in and goes out each month, while net worth shows the cumulative difference between what one owns and what one owes.
As a financial organization practice, you can create a spreadsheet with two main columns: assets and liabilities. The first column lists savings, investments, and property; the second lists outstanding debts. You then total both columns and subtract the sum of the liabilities from the sum of the assets. Repeating this exercise every six to twelve months allows you to observe changes and make better-informed decisions, such as allocating more resources toward paying off high-interest debt, strengthening an emergency fund, or adjusting savings goals. This result should be used as a planning tool rather than as the sole measure of financial well-being.
You may also want to read: